
Challenge Fee Tracking: Count Every Attempt Cost
Build a receipt-based record of purchases, resets, refunds and missing evidence without mixing fees with simulated trading results.
On this page
QUICK ANSWER
Give every attempt a stable identity, attach each evidenced purchase or reset once, preserve original currencies and record refunds separately. Keep simulated P&L outside the cash ledger and mark missing evidence instead of guessing. The result should help you ask better questions, not promise recovery or justify another purchase.
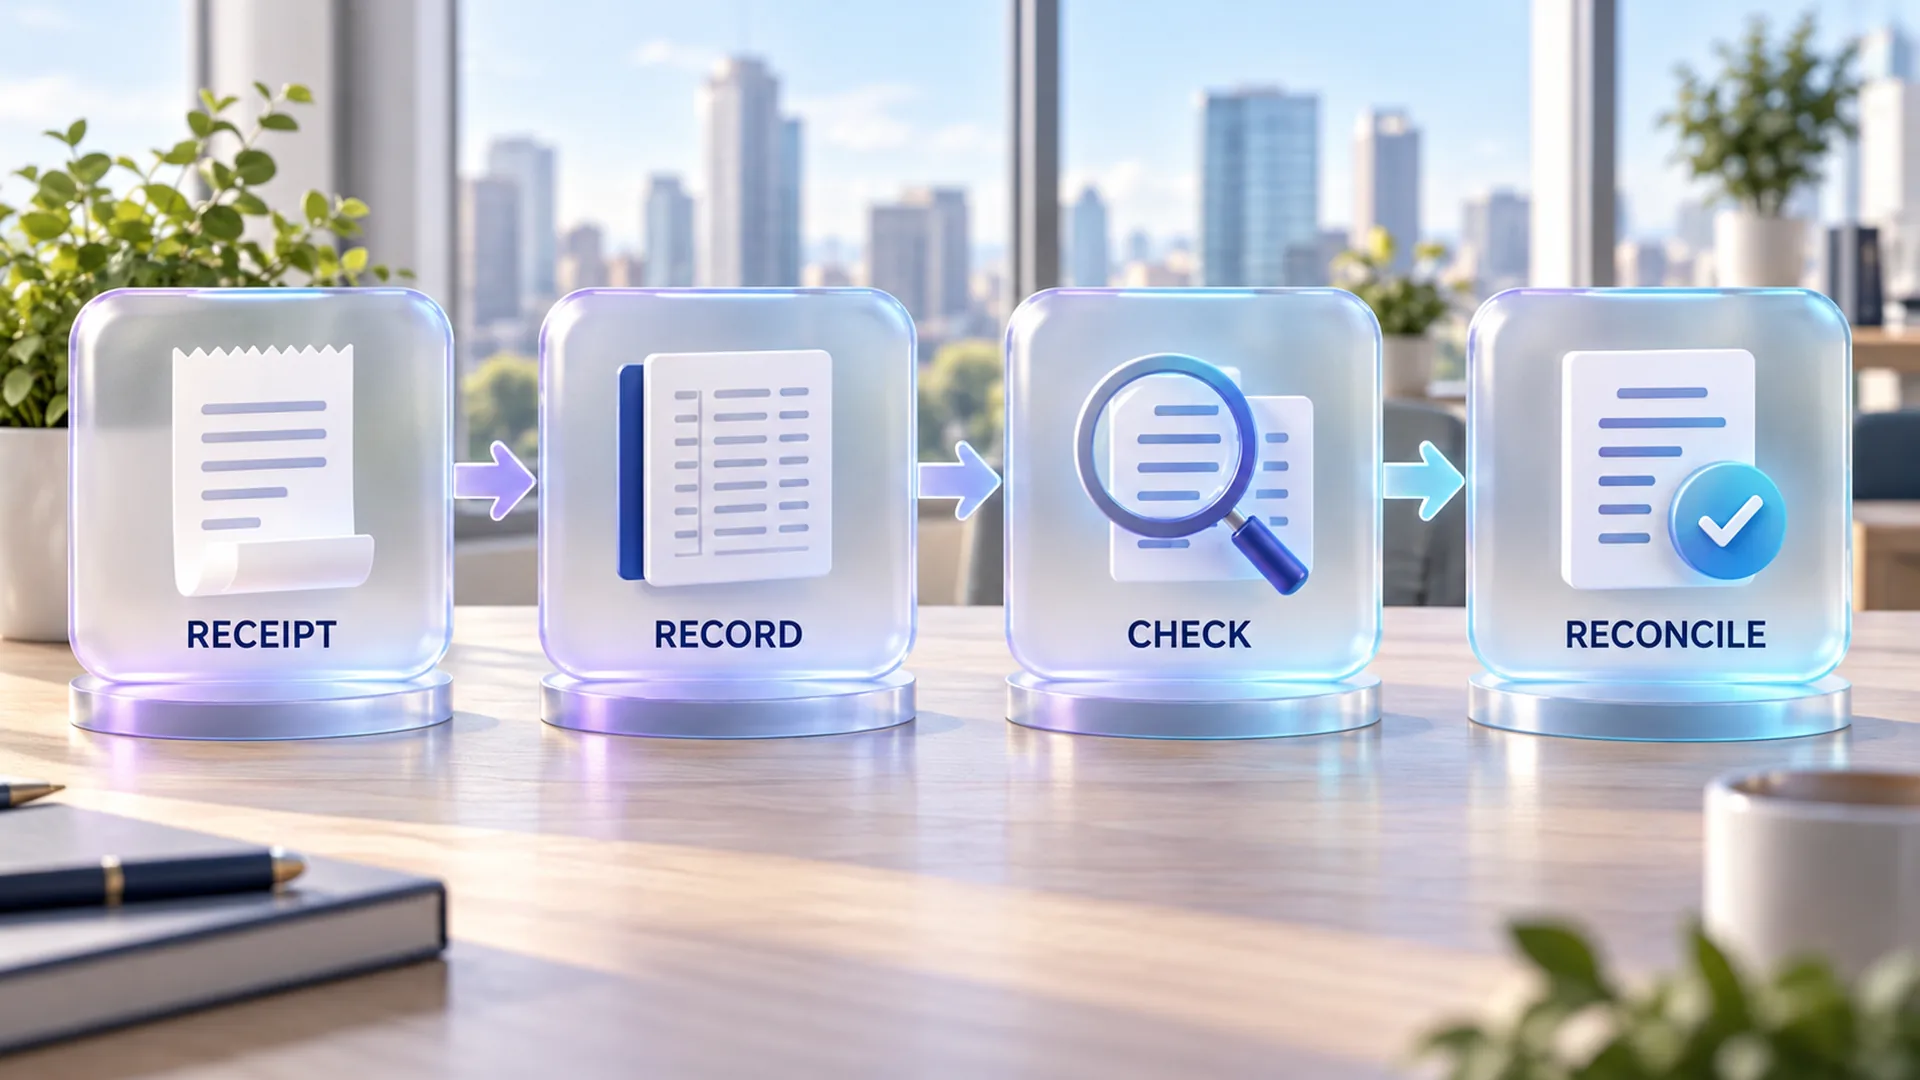
The four-part map keeps identity, money and evidence connected while leaving unsupported information visibly unresolved.
Start with the attempt record, then reconcile every transaction that belongs to it.
Challenge fees can disappear into email folders, payment statements and memories of earlier attempts. A clean ledger brings those records together without turning them into a story about what you should buy next. The examples below are fictional and teach the method; they are not typical-spending claims, firm rules, tax advice or personal financial advice.
Use the recorded terms as a starting point, then reopen the provider’s current official page. Compare programme, stage, drawdown method and restrictions without treating an old screenshot as the final answer.
BUILD THE FOUNDATION
Give Every Attempt Its Own Record
A fee ledger becomes useful only when each payment belongs to one clearly identified evaluation attempt. Start with identity, then add money.
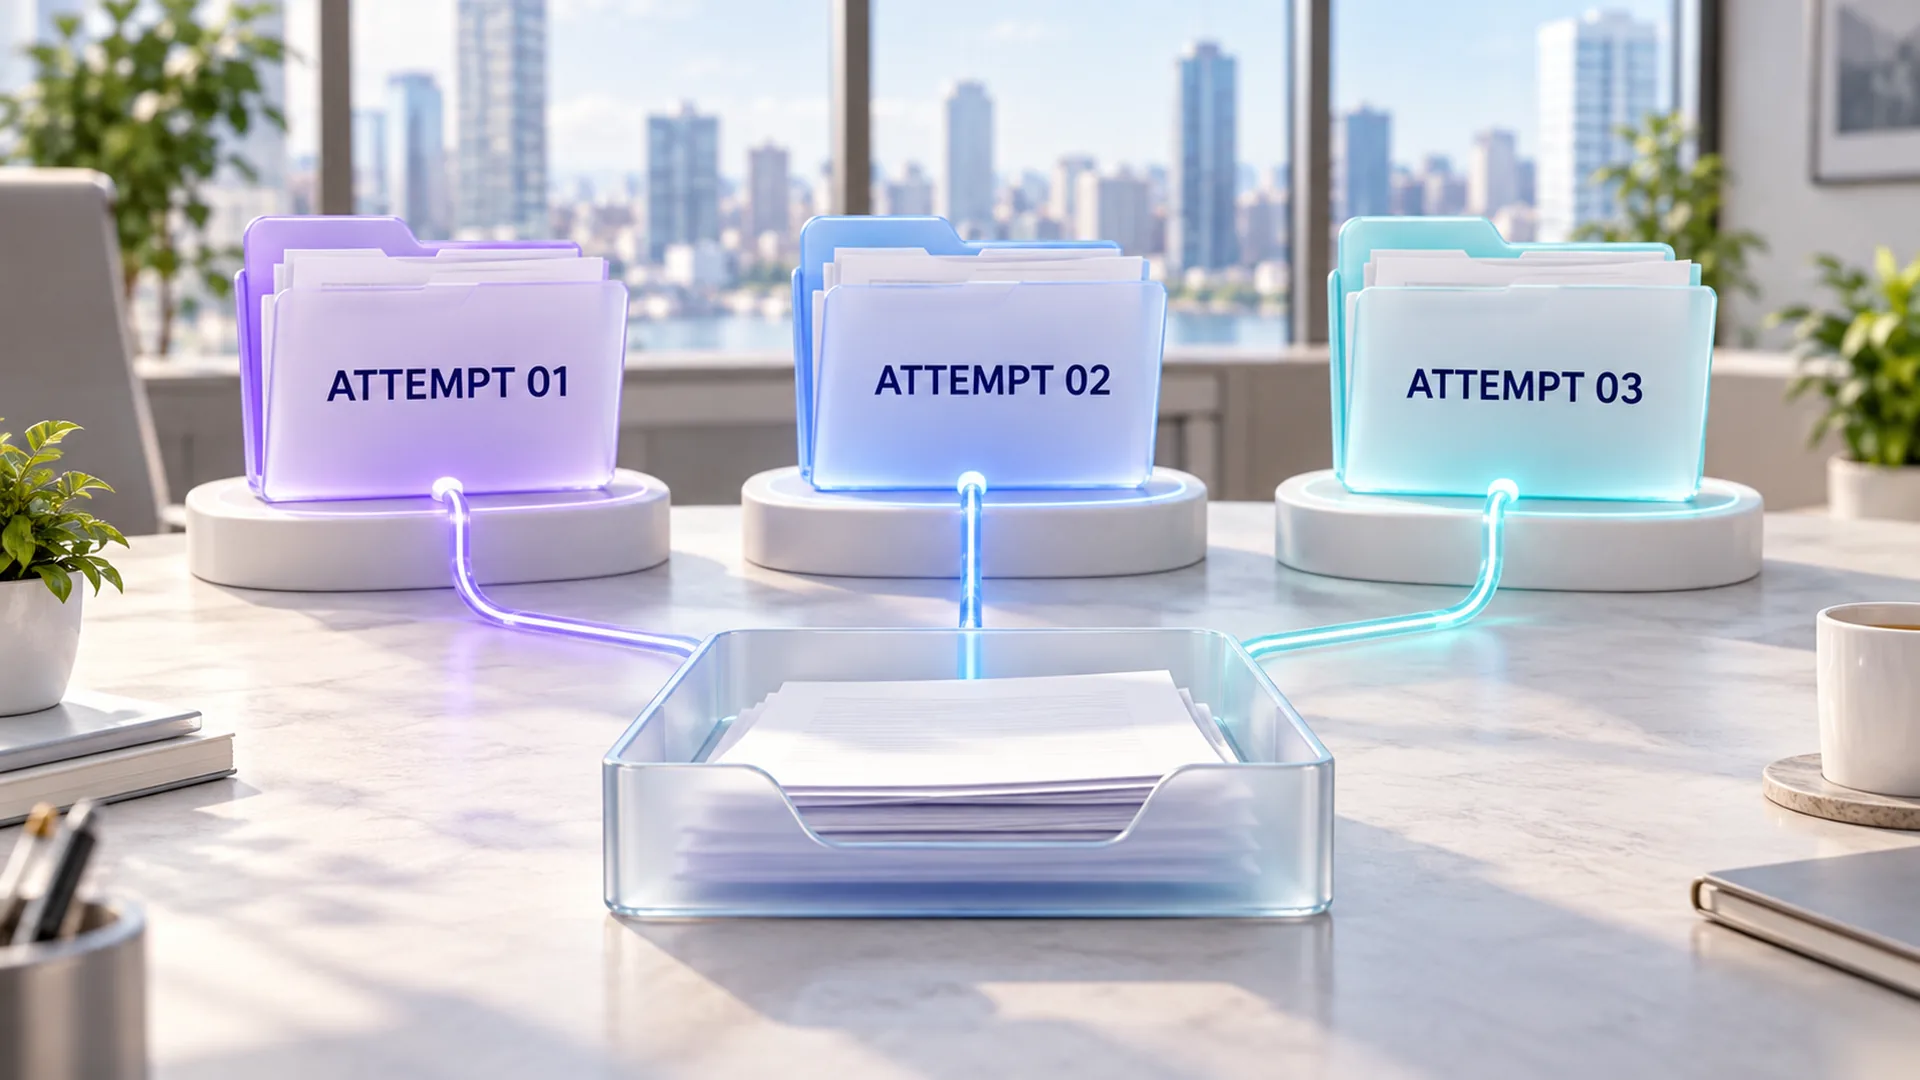
Why does every evaluation attempt need a separate identity?
A separate attempt identity prevents one purchase, reset or refund from drifting into another record. Use a neutral label such as Provider–Programme–Year–Attempt 01. The label is an organising key, not a judgement about success or failure, and it should remain stable when later evidence arrives.
At a glance
- Provider
- Who supplied the programme?
- Programme
- Which exact evaluation was purchased?
- Attempt ID
- Which numbered record owns the transaction?
The three fields turn a vague memory into a record that another person could follow.
Once the identity is fixed, decide what evidence belongs beside it.
What evidence should sit beside an attempt record?
Keep the purchase confirmation, transaction date, original amount, original currency and a private receipt reference. Record the programme and account phase shown by the evidence. Do not publish full card numbers, order codes or personal data. The ledger needs a traceable reference, not exposed confidential information.
At a glance
- Receipt reference: a private locator, with sensitive characters hidden.
- Original transaction: date, amount and currency as charged.
- Programme context: provider, programme and account phase.
A compact evidence bundle supports later checking while keeping sensitive details out of the public article.
With the evidence grouped, the next job is to define each transaction type.
How should purchase, reset and refund entries be labelled?
Label each transaction by what the evidence shows: original purchase, reset, evidenced refund or evidenced payout receipt. Never rename a reset as a new challenge merely to simplify totals. Keep cash records separate from simulated account figures. Clear labels make duplicate charges and unsupported assumptions easier to spot.
At a glance
- PurchaseInitial access charge
- ResetSeparate restart charge
- RefundCash returned, only when evidenced
The lanes preserve the transaction’s meaning before any totals are calculated.
That prepares the ledger for a transaction-by-transaction reconciliation.
A structured learning environment can help you rehearse record checks and decision pauses. It should not replace the exact programme terms or personal responsibility.
RECONCILE THE EVIDENCE
Reconcile Purchases and Resets
A clean reconciliation joins each charge to one attempt, detects duplicate rows and leaves missing receipts visible instead of filling gaps.
How do you build the first reconciliation table?
Enter one evidenced transaction per row. Give it an attempt ID, transaction type, date, original amount, currency and receipt status. If one receipt covers several items, preserve that fact in the note rather than splitting the amount without evidence. The first aim is traceability, not a persuasive total.
At a glance
| Attempt | Type | Amount | Evidence |
|---|---|---|---|
| A-01 | Purchase | £89 | Receipt held |
| A-01 | Reset | £39 | Receipt held |
| A-02 | Purchase | €99 | Missing |
The fictional rows show structure only. The euro entry remains outside a sterling subtotal until a documented conversion basis exists.
Before adding totals, check whether any row has been entered twice.
How can you detect a duplicate fee without guessing?
Compare the private transaction reference, charged amount, currency, date and attempt ID. An exact match is a strong duplicate signal, but similar amounts on different dates may be separate purchases. Mark uncertain pairs for review. Delete or merge a row only when the underlying evidence supports that action.
At a glance
The review key narrows the check. It does not automatically prove that two transactions are the same.
After duplicates are controlled, calculate only within clearly defined boundaries.
What total can a challenge fee ledger safely show?
State the period, included transaction types and currency beside every subtotal. Sum documented purchases and resets once. Show evidenced refunds separately, then label any net-fee subtotal. Do not combine currencies through an invented rate, subtract simulated profit or treat a blank payout field as confirmed zero cash received.
Fictional documented GBP fee breakdown
The fictional GBP purchase of £89 plus the £39 reset equals £128 in documented fees. No evidenced refund reduces that subtotal. The unresolved €99 entry remains outside the sterling chart, and the figures do not represent typical trader spending.
The numbers are clearer now; the harder question is how to review repeated spending calmly.
PAUSE BEFORE ANOTHER PURCHASE
Review Repeat Spending Without Purchase Pressure
A ledger should improve visibility, not push the reader towards buying again or promise that a future attempt will recover earlier costs.
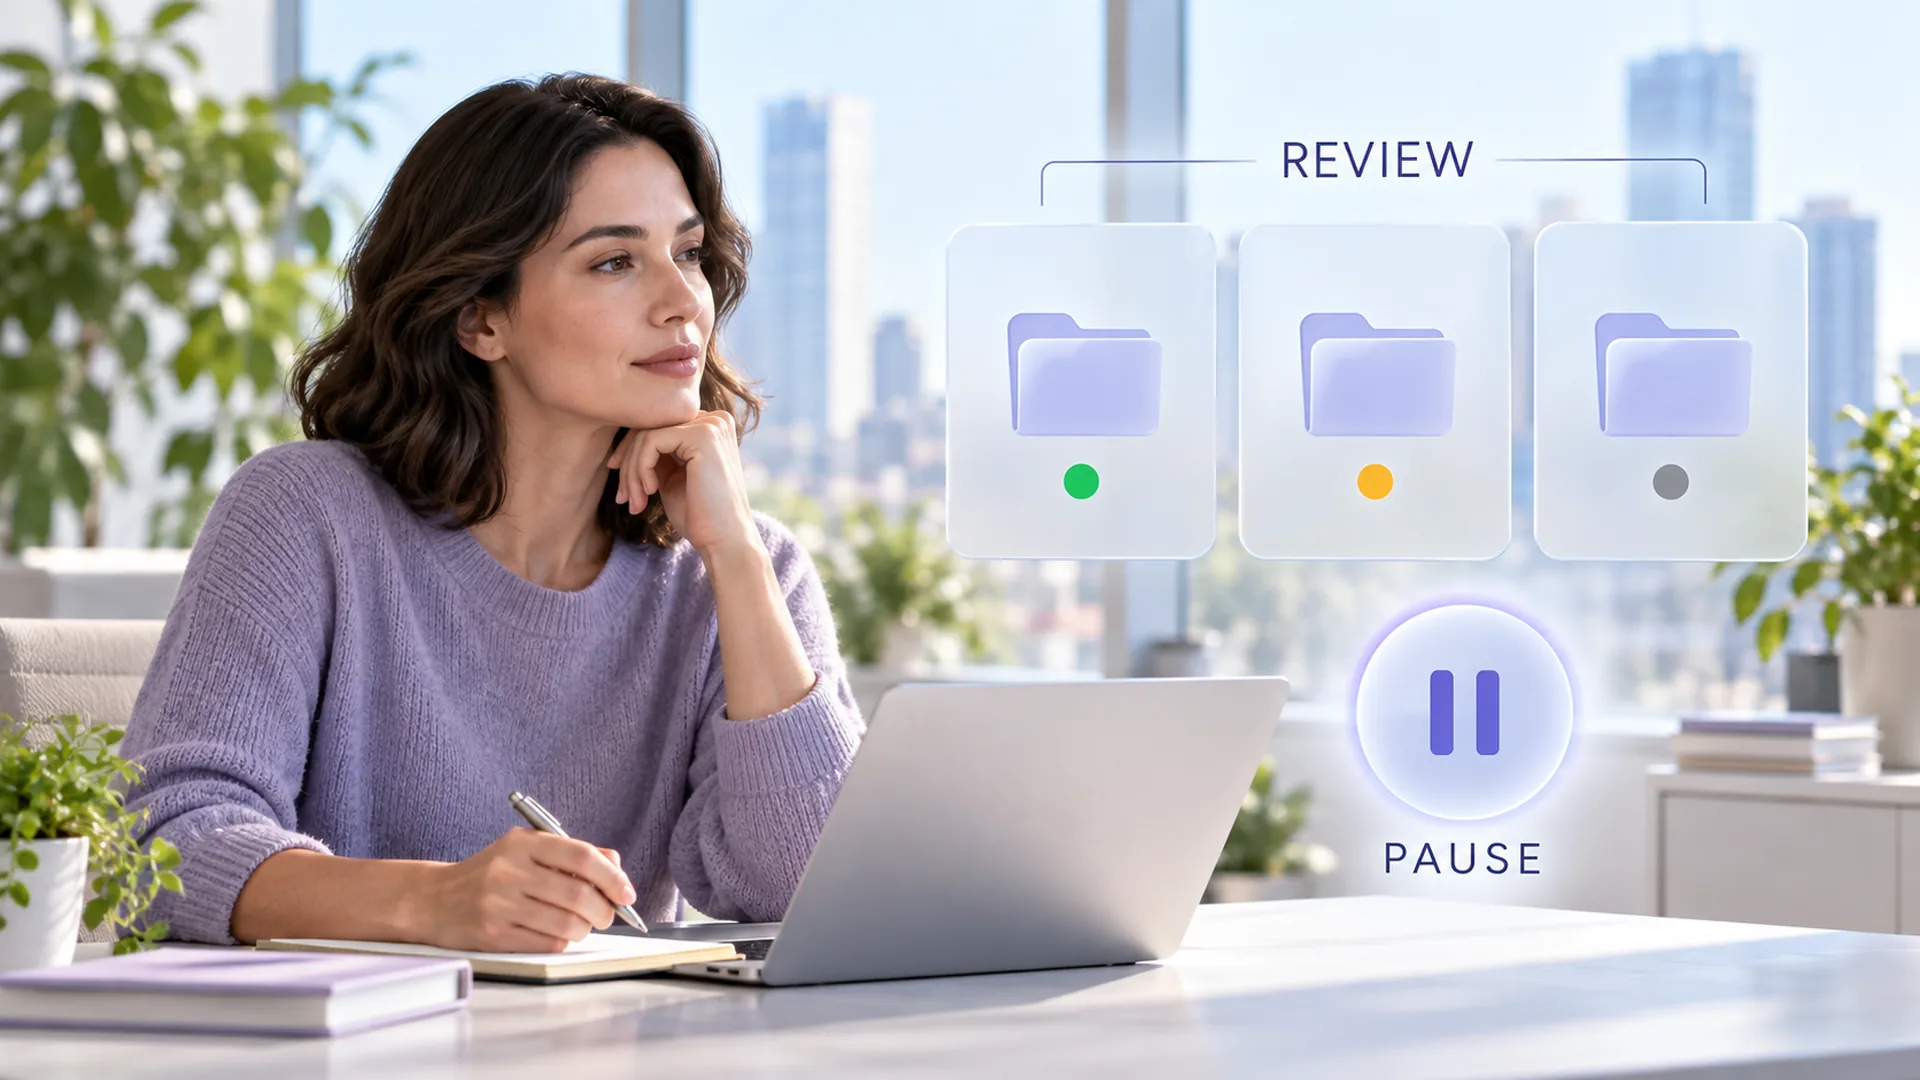
Why should failed and abandoned attempts stay in the record?
Removing an unsuccessful or unfinished attempt makes the spending history incomplete. Keep it with a neutral status such as completed, failed, abandoned or unresolved, using only evidence you possess. The status explains what happened to the record; it does not diagnose the trader or predict the value of another attempt.
At a glance
A neutral status vocabulary preserves the full history without turning the ledger into a score of personal worth.
The next step is to separate what the evidence says from what you feel about it.
How can you separate documented cost from regret or urgency?
Put the amount and evidence status in factual columns. Put reflections in a separate note. A receipt can prove a charge; it cannot prove that another purchase is wise, that earlier spending must be recovered or that a trader is ready. This separation makes emotional pressure visible without pretending to measure it.
At a glance
- Documented
- Charge, date, currency, receipt status
- Reflective
- Pressure, regret, uncertainty, reasons to pause
Two columns prevent a real payment from becoming an argument for the next one.
Use that separation to create a short pause checklist.
What should you check before adding another evaluation fee?
Review the complete ledger, unresolved receipts and the reason the previous attempt ended. Confirm the current programme terms separately. Decide whether pausing, practising or not purchasing is appropriate. The worksheet organises questions; it cannot determine personal affordability, suitability or trading readiness for you.
At a glance
- Evidence check
Resolve missing or duplicate records before relying on the total.
- Purpose check
Write what a new purchase is expected to change.
- Pause option
Keep no purchase as a valid, visible outcome.
The three checks create space between reviewing past spending and making a fresh commercial decision.
Next, keep account-access fees separate from trading-session figures.
KEEP DIFFERENT NUMBERS APART
Separate Fees From Session Results
Evaluation charges, execution costs, simulated P&L and cash receipts answer different questions. Combining them can create a misleading story.
What is the difference between an evaluation fee and a trading cost?
An evaluation fee is a cash charge for access to a programme. Spreads, commissions and financing are execution-related figures within a trading account or session. Record them in separate ledgers unless a clearly stated analysis needs both. Their labels, evidence and meaning should remain distinct even when reviewing one period.
At a glance
Four drawers prevent one kind of number from silently changing the meaning of another.
The most common confusion is between simulated account results and money received.
Why must simulated P&L remain separate from cash receipts?
A simulated account result is not the same record as money entering or leaving a bank or payment account. Keep payout eligibility, requested payouts and evidenced received payouts separate. A blank receipt field means evidence is unavailable in the ledger; it does not prove that no payment existed or that a provider was at fault.
At a glance
Simulated P&L and account events
Purchase, refund and received-payout evidence
The boundary keeps the worksheet focused on documented cash movement while preserving account outcomes as different evidence.
A worked table shows how those categories can coexist without being netted together.
How should the categories appear in one review?
Use a category summary that shows separate subtotals and evidence status. Never present one “profit after fees” figure unless every component is comparable, supported and appropriate for that calculation. For this guide, the safer view is parallel: fees paid, refunds evidenced, payout receipts evidenced and simulated account results recorded elsewhere.
At a glance
| Category | Example | Treatment |
|---|---|---|
| Documented evaluation fees | £128 | £89 purchase + £39 reset |
| Refunds | £0 evidenced | Show separately |
| Unresolved EUR fee | €99 | Keep outside GBP subtotal |
| Simulated P&L | Not shown | Different record |
| Payout receipts | Unavailable | Do not infer zero |
The fictional table carries the same dataset forward: £128 in documented GBP fees, no evidenced refund and an unresolved €99 fee kept separate. Simulated P&L is not shown, and unavailable payout-receipt evidence is not treated as zero.
With categories separated, the ledger can handle currencies and gaps honestly.
AI can help arrange records and prompt questions, but every factual entry still needs evidence and human responsibility. Do not let an automated summary invent missing amounts.
MAKE UNCERTAINTY VISIBLE
Keep Currencies and Missing Records Visible
Useful challenge fee tracking preserves original units and shows what is unknown. Hidden assumptions can make a neat total less accurate.
How should a ledger handle fees charged in different currencies?
Keep each original amount and currency exactly as recorded. Produce separate currency subtotals unless you have a documented conversion basis, date and rate source. If you convert for a defined purpose, retain both the original and converted values. Never invent a rate simply to create one impressive grand total.
At a glance
The £128 GBP subtotal contains the documented £89 purchase and £39 reset. The unresolved €99 fee stays in its original currency and outside the GBP subtotal; no combined total is invented.
Currency is one kind of gap; missing receipts require their own explicit status.
What should you write when a receipt is missing?
Mark the evidence as missing, note where you searched and record the next practical question. Do not reconstruct an exact amount from memory and present it as documented. If a bank line exists without a provider receipt, label that narrower evidence accurately. The record may be incomplete while still remaining useful.
At a glance
- MarkMissing, partial or conflicting
- SearchEmail, payment account and provider records
- AskOne focused support question
- PreserveThe unresolved status until evidence arrives
The path converts a blank cell into a controlled unresolved item without fabricating an answer.
Real reader questions can reveal where the worksheet needs clearer guidance.
What publicly raised questions add context to a fee ledger?
Public discussions raise questions about firm incentives, post-purchase clarity, trust and how fees enter a wider evaluation. The four questions below are faithful paraphrases, linked to publicly named sources. They provide context for better due diligence; they do not verify a particular firm, quantify typical costs or answer personal suitability.
Reader questions · faithful paraphrases
- Martin Najat
- How can a prop firm generate revenue independently of trader performance?
- Public LinkedIn source
- Adesuyi Adebola Emmanuel
- What is one thing a prop firm should explain more clearly after a trader signs up?
- Public LinkedIn source
- Jeremy Kinstlinger
- How can a trader trust a firm if trader success is treated as its risk rather than its goal?
- Public LinkedIn comment
- Thomas Skinner
- How should challenge fees, failed-challenge fees, activation fees and resets enter a wider programme assessment?
- Public LinkedIn source
These questions show why a fee ledger needs context: document cash records first, then investigate incentives, communication, trust and analytical assumptions through their own evidence.
The final section turns the reconciled record and those wider questions into practical next steps.
Match the provider, programme, account type and stage. When records conflict, preserve the dated evidence and ask one precise question.
TURN RECORDS INTO QUESTIONS
Use the Record for Better Questions
The finished ledger is not a verdict. It is a clearer starting point for resolving evidence gaps, reviewing decisions and choosing a bounded next action.
What questions should a completed fee ledger help you answer?
It should show how many evidenced attempts exist, which charges belong to each attempt, which resets are separate, which refunds or payout receipts are evidenced and which records remain unresolved. It should also reveal where currencies prevent one subtotal. These are record questions, not predictions about future trading performance.
At a glance
The compass keeps the review centred on evidence and next questions rather than a promise of recovery.
Turn those questions into a small action list rather than another large administration system.
What are the three most useful actions after reconciliation?
First, request one missing record or clarify one conflicting transaction. Second, archive the current ledger with its review date so later evidence cannot overwrite history silently. Third, decide the next bounded action, including a pause. Avoid creating repeated weekly paperwork when no underlying transaction has changed.
At a glance
- Resolve one gap
Ask for a missing receipt or clarify a duplicate.
- Save one snapshot
Date the accepted ledger and preserve its evidence links.
- Choose one bounded action
Continue, practise or pause without a recovery promise.
A short action list turns the ledger into useful follow-through without making it another bureaucratic burden.
The final step is deciding what this worksheet can and cannot tell you.
What is the final takeaway from challenge fee tracking?
Count every evidenced attempt cost once, preserve the original currency and keep purchases, resets, refunds, payout receipts and simulated results in their proper categories. Leave missing evidence visible. A reliable ledger improves your questions and memory; it cannot guarantee profitability, determine tax treatment or decide whether another challenge suits you.
At a glance
The process finishes with an honest record: complete where evidence exists and visibly incomplete where it does not.
The Blog is complete. Use the poll, next moves, sources, disclaimer and FAQs below as supporting material.
📊 Quick poll
Which part of challenge fee tracking is hardest to keep clear?
Sources and evidence context
- Accepted R26 Monday weekly research package, dated 11 October 2026, including PAIN-MON/C1 and its recorded limitations.
- Martin Najat on prop-firm economics — publicly named source; displayed reader question is a faithful paraphrase.
- Adesuyi Adebola Emmanuel on post-signup clarity — publicly named source; displayed reader question is a faithful paraphrase.
- Jeremy Kinstlinger’s public comment on trader–firm incentives — publicly named source; displayed reader question is a faithful paraphrase.
- Thomas Skinner on modelling programme economics — publicly named source; displayed reader question is a faithful paraphrase.
- SWL payout-request evidence guide — neighbouring intent only.
- SWL rule-version audit guide — programme applicability.
Search demand, regional volume and Search Console evidence are UNKNOWN. Fictional figures demonstrate record structure only.
Disclaimer
This educational guide does not provide financial, trading, legal or tax advice. Prop-firm terms vary by provider, programme, account type and date. Verify current official terms and your own payment records. Trading and evaluation fees can result in financial loss. The worksheet does not predict performance, guarantee payouts or decide whether another purchase is appropriate.
